

Till: Debit Card for Kids
by Till Financial
4.5
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.5
- Price
- Free
- Download
- 100.00K
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
 Analysis by Getfullapps
Managing money is difficult enough for adults, so giving a child a debit card can feel like a big step. I found Till: Debit Card for Kids most useful when treated as a guided learning tool rather than a miniature bank account. It gives families a way to discuss spending in everyday situations, while the child gets a more direct connection between a purchase and the money behind it. That makes it especially interesting for parents who want practice to happen outside a purely theoretical allowance conversation.
The app comes from Till Financial and belongs to the finance category. It is free to download, rated for Everyone, and has passed the early-experiment stage with more than one hundred thousand installs. Its average rating sits at 4.5 from around 2.2 thousand ratings, which suggests that many families find the basic idea worthwhile. I would still judge it by the household’s needs, because a child’s age, reading confidence, attention span, and need for independence can change the experience considerably.
How clearly Till works for different users
I find the most useful way to judge Till is to ask whether its shared spending routine can adapt as a child’s confidence changes. A parent may need close guidance at first, while a teenager may benefit from more room to make ordinary choices and discuss them afterward. That distinction matters because a tool is only helpful when its level of involvement suits the person using it.
Readable navigation for a parent and child
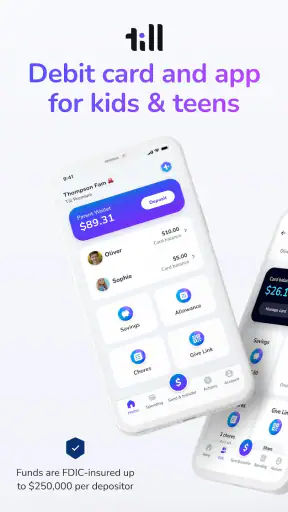
My first impression is that Till is easier to understand when the adult and child use it as a shared routine. The central concept is straightforward: the child has a debit card, and the app helps the family connect that card with spending decisions. That is a much more concrete lesson than simply handing over cash and asking the child to remember where it went. A parent can use the app as the place to review what happened, while the child can begin to see spending as a sequence of choices rather than an unlimited resource.
That simplicity matters for families with different levels of financial knowledge. A parent who is comfortable with banking apps can usually approach Till as part of an existing money-management habit. Someone who dislikes complicated financial tools may appreciate that the product is focused on a young person’s spending rather than trying to replace every adult banking service. For a child, the card offers a tangible object and the app supplies the surrounding context.
I would introduce it with one small task at a time. For example, I might show a child how to check the balance before leaving for a school event, then discuss whether the available money covers a planned snack. Later, I would review the purchase together and ask whether it matched the original plan. This workflow is more accessible than giving a child a long explanation about budgeting all at once. It also turns the app into a prompt for conversation instead of another screen demanding attention.
The developer’s choice to position Till around smarter spending is important here, but the phrase should not be interpreted as automatic financial education. The app can support a lesson; it cannot have the lesson on the parent’s behalf. Younger children may need an adult to translate a balance into a practical decision, while older children may want more privacy and control. I see the best results when the family agrees in advance about what will be checked, what the child can decide alone, and when a discussion will happen.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
Motor and sensory considerations in ordinary use
For motor access, the main advantage is that a debit-card routine can reduce the need for a child to handle cash, count coins, or keep receipts safe. That can be helpful for someone who finds small objects, handwriting, or multi-step physical tasks frustrating. The app also keeps the financial activity in a digital setting, which may be easier for a child already comfortable using a phone. Still, a digital card-management experience is not automatically easy for every user. Tapping accurately, moving between screens, and reading small amounts of information can remain tiring.
I would avoid assuming that a child who can use games or video apps will automatically find a finance app comfortable. Money screens often require slower reading and more careful attention. A child with dyslexia, limited literacy, attention differences, or difficulty processing numbers may benefit from an adult reading key information aloud and connecting it to a specific example. The strongest accessibility improvement may therefore come from the family’s routine: use plain language, pause between steps, and avoid asking the child to make a decision while rushed.
Sensory context matters as well. A busy shop, noisy school trip, or crowded checkout is a poor place to teach a new financial workflow. If a child becomes overwhelmed by sound, time pressure, or social attention, checking the balance and deciding whether to buy something may be harder than the app itself. I would practice at home first, using a pretend shopping list and a calm review afterward. That gives the child a chance to learn the sequence without the pressure of other people waiting.
One useful approach is to separate the card action from the learning conversation. The child can make a purchase when the situation requires speed, and the adult can discuss it later in a quieter setting. This avoids turning a public mistake into a public correction. It also helps children who need extra processing time. Till is more inclusive when it supports that slower follow-up rather than being treated as a test the child must pass at the checkout.
Situational access: where the app fits well
A realistic use case is a child attending a weekend activity with a small amount available for food or a personal item. Before leaving, the parent and child can agree on the purpose of the money and talk through one or two choices. At the event, the child has a practical reason to think before spending. Later, the family can look back at what happened and decide whether the plan worked. This is more meaningful than a generic lecture because the child has a real memory attached to the decision.
Till can also suit families who want to move gradually from cash allowances toward independent spending. Cash is visible and familiar, but it can be lost, forgotten, or difficult to track after several purchases. A debit card creates a different kind of learning: the child must understand that a balance changes even when there is nothing physical left in their hand. That trade-off is valuable, although it means parents should explain digital money carefully. A child may otherwise think that tapping a card is somehow separate from using money.
The app may be a good fit for a teenager preparing for more independence, particularly when the family wants spending practice without handing over an unrestricted adult account. It can create a middle stage between parental purchasing and fully self-directed banking. I would not use it as the only financial education, though. Teenagers still need conversations about recurring expenses, saving for a goal, online purchases, scams, and what to do when a transaction looks unfamiliar. A child-focused debit card can open those discussions, but it does not replace them.
Compared with a cash envelope, Till offers a more direct connection to card-based shopping and avoids the need to carry change. Compared with adding a child to an ordinary adult account, its child-and-family focus is more appropriate for teaching spending boundaries. The compromise is that families seeking a complete household budgeting system may find a dedicated child card too narrow. Adults who already have a preferred bank, budgeting app, or allowance method may not want another financial workflow to maintain.
Practical friction and remaining barriers
The biggest barrier is not necessarily navigation; it is the responsibility placed on the adult. A parent has to decide how much independence is appropriate, explain the rules, and revisit them as the child grows. If the app is installed but rarely discussed, the card can become just another payment method. That weakens the educational value and may leave the child confused about why a purchase succeeds one time but becomes a conversation another time.
Families should also think about whether a child is ready to manage a balance without becoming anxious. Some children may check constantly, worry about making a mistake, or feel embarrassed when they need help. Others may spend quickly because digital payment feels less real than cash. I would begin with a clearly defined purpose and a modest routine, then increase independence only after the child can explain the basic consequences of spending.
There is also a difference between access and control. A parent may find it reassuring to stay involved, while a teenager may experience frequent oversight as intrusive. Till works best when supervision changes over time. A family could start with joint reviews, move toward occasional check-ins, and let the teenager handle more decisions as their judgment develops. If the household cannot agree on that progression, the product may create arguments instead of confidence.
The in-app purchase range, from $7.99 to $79.00 per item, is another point I would consider before committing to a longer-term setup. The download itself is free, but families should look carefully at what they may choose to pay for inside the app and whether those costs fit their intended use. I would not assume that every household needs every optional purchase. A parent should decide on a budget for the service before involving the child, so the financial lesson does not become confused with surprise spending on the tool itself.
Device compatibility is also worth checking in practical terms. The listed minimum operating-system requirement is Android 7.0, and the current version is 162.41.0. That makes the app relevant to many older Android phones, but an operating-system number alone does not guarantee that every device will feel comfortable to use. Screen size, text rendering, battery condition, and the child’s familiarity with the phone can all affect access. I would test the everyday workflow on the actual device the child will carry, not only on the parent’s newer phone.
Who should choose it, and who should look elsewhere?
I would recommend Till to a parent who wants a structured way to introduce card spending and is prepared to stay involved. It is particularly suitable for a child who learns best through real examples: checking available money before an outing, making a limited purchase, and reviewing the result afterward. It can also help a family replace an untracked cash allowance with a routine that produces clearer spending conversations.
I would be more cautious if the child is not ready to connect a digital payment with a reduced balance. In that case, cash or a simple visual allowance system may teach the first lesson more clearly. I would also look at other options if the family needs advanced household budgeting, detailed financial planning, or a banking arrangement designed primarily for adults. Till’s strength is the child-focused bridge into spending, not the promise of being the only money tool a family will ever need.
For children with reading, motor, attention, or sensory differences, I would not make a decision from the product category alone. I would try the key tasks with support: opening the app, finding the relevant money information, understanding what a purchase means, and recovering calmly from a mistake. If those steps are manageable with a consistent routine, the app may be useful. If the child needs a highly customized interface, extensive visual supports, or an especially low-distraction environment, a different solution may be more comfortable.
My inclusive verdict after using the whole workflow
What I like about Till is the way it places a child’s spending inside a family conversation. The card makes money feel real, while the app gives the parent and child a reason to review choices together. That combination can support independence without pretending that independence means being left alone. The product is at its most inclusive when adults adapt the pace, language, and timing to the child rather than expecting every child to use the same routine.
What I would not do is hand over the card and call the financial lesson complete. The app cannot remove the need for clear boundaries, patient explanations, or a plan for mistakes. It also may not suit families who want a broad adult banking replacement or children who find digital numbers too abstract. Those are not small details; they determine whether the experience feels empowering or confusing.
Overall, I see Till: Debit Card for Kids as a useful stepping stone for families ready to teach spending through supervised practice. Its free entry point and Everyone rating make it approachable, while its reception of a 4.5 average and more than one hundred thousand installs shows that it has found a substantial audience. My recommendation is to start with one predictable use case, agree on how support will work, and review the experience with the child. Used that way, Till can make everyday money decisions clearer and more inclusive without rushing a young person into adult financial responsibility.
Pros
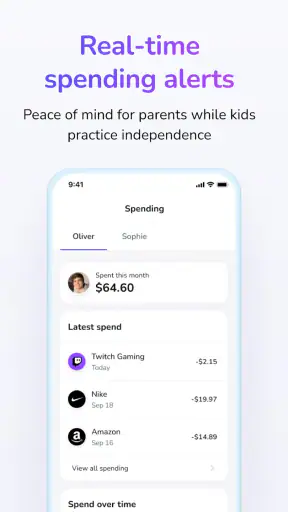
- Parents can set spending limits and monitor transactions in one place.
- Kids receive practical money-management experience with controlled independence.
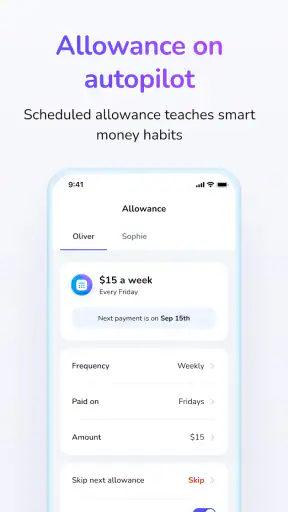
- The app supports allowances and recurring payments for easier family routines.
- Real-time notifications help parents spot purchases as they happen.
- A dedicated card reduces the need to give children cash for everyday spending.
Cons
- Availability and features may vary depending on the country and card program.
- Some advanced controls or services may require a paid subscription.
- Children need access to a compatible smartphone for the full app experience.
- Card usage depends on merchant acceptance and a reliable payment network.
- Parents must remain involved to review activity and teach responsible spending.
FAQs for Till: Debit Card for Kids
What is Till: Debit Card for Kids, and how does it work?
Till is a family-focused debit card and money-management app designed to help children learn how to spend, save, and manage money under parental supervision. Parents typically create and control the account, add funds, review transactions, and set expectations, while children use their card for approved purchases. Availability, features, and account requirements may vary by location.
What age is Till suitable for, and does a parent need to open the account?
Till is intended for children and teenagers, but the exact eligible age range depends on the provider’s current terms and the user’s country or state. A parent or legal guardian generally needs to create the account, complete identity verification, and remain responsible for the account. Before downloading, review the latest eligibility rules and required documents.
Can parents control spending and monitor transactions with Till?
Yes, parental oversight is one of Till’s main purposes. Depending on the available plan and region, parents may be able to add money, view purchases, receive transaction updates, manage card settings, and discuss spending habits with their child. It is still important to check transactions regularly, because app controls and notification options may change with updates.
Are there fees, spending limits, or restrictions on the Till debit card?
Potential costs and limitations can include subscription charges, card replacement fees, ATM fees, transfer restrictions, or limits on daily and monthly spending. Some features may only be available with a particular plan, and certain merchants or transaction types may not be supported. Carefully read Till’s current pricing, cardholder agreement, and fee disclosures before signing up.
Is money held in Till protected, and what should I do if the card is lost?
The protection available for funds depends on how Till provides its account services, the partner financial institution, and the laws applicable to your location. Parents should review the app’s disclosures for information about safeguarding, insurance, and dispute procedures. If a card is lost, stolen, or used without permission, freeze it through the app if possible and contact Till support promptly.

Till: Debit Card for Kids
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via support@tillfinancial.io, visit https://tillfinancial.io, or review their https://tillfinancial.com/privacy.










